
GLOBAL CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Global Contrast Ultrasound Market by Product (Equipment, Contrast Agents) Market by Type (Non-Targeted, Targeted) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by End Use (Hospitals, Clinics, Ambulatory Diagnostic Centers), by Geography
REPORTS » HEALTHCARE » MEDICAL DEVICES » GLOBAL CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
GLOBAL CONTRAST ULTRASOUND MARKET OVERVIEW
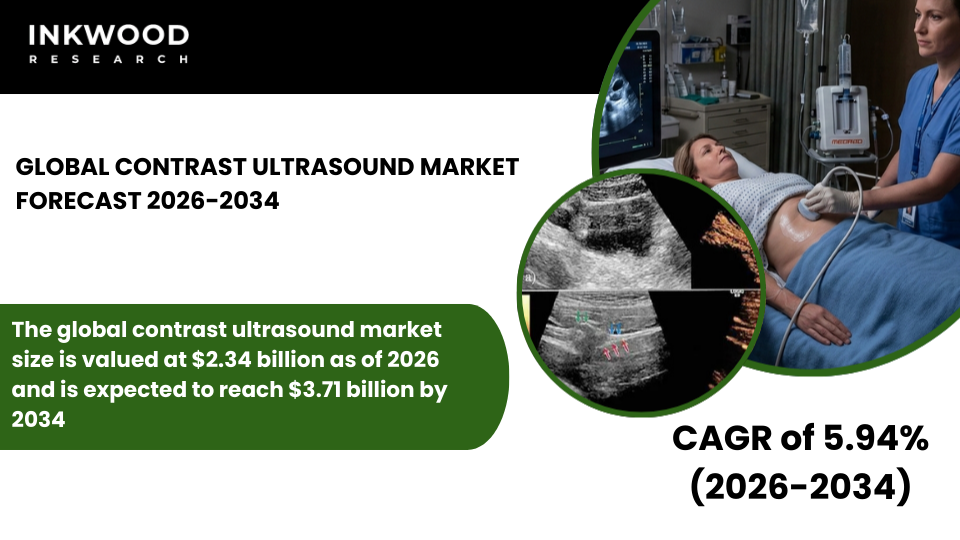
The global contrast ultrasound market size is valued at $2.34 billion as of 2026 and is expected to reach $3.71 billion by 2034, growing at a CAGR of 5.94% during the forecast period 2026-2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the contrast enhanced ultrasound market qualitatively as well as quantitatively.
Contrast enhanced ultrasound is an advanced imaging technology that uses microbubble-based contrast agents to improve the visualization of blood flow and tissue perfusion in real-time. Unlike traditional ultrasound, this technique relies on injectable contrast agents (typically composed of gas-filled microbubbles encapsulated in protein or lipid shells) that enhance the acoustic reflectivity of blood. Consequently, physicians gain clearer insights into vascular structures, organ perfusion patterns, and tissue abnormalities.
Moreover, contrast ultrasound offers a radiation-free alternative to computed tomography (CT) and magnetic resonance imaging (MRI), making it particularly valuable in pediatrics, oncology, and cardiology. The technology supports both diagnostic imaging and emerging therapeutic applications, including targeted drug delivery and tumor ablation monitoring.
The global contrast ultrasound market is experiencing steady growth due to several converging factors. The rising prevalence of cardiovascular diseases and liver disorders has intensified the need for accurate, non-invasive diagnostic tools. Additionally, growing preference for radiation-free imaging modalities is driving adoption among healthcare providers and patients alike.
Technological advancements in portable ultrasound devices and software application diagnostic and therapeutic capabilities have further expanded clinical utility. Furthermore, increasing integration of artificial intelligence in diagnostic imaging is enhancing the precision and efficiency of ultrasound procedures. These trends, combined with expanding reimbursement frameworks in developed markets, are propelling market expansion across North America, Europe, and the Asia-Pacific.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global contrast ultrasound market growth:
- Rising prevalence of cardiovascular diseases and liver disorders is increasing demand for enhanced diagnostic accuracy
- Growing preference for minimally invasive and radiation-free imaging techniques is boosting contrast ultrasound utilization
- Technological advancements in ultrasound systems are improving image resolution and clinical confidence
- Expanding clinical applications in pediatrics and interventional radiology are broadening market opportunities
- Expanding clinical applications in pediatrics and interventional radiology represent a significant driver for the contrast enhanced ultrasound market. Pediatric imaging demands radiation-free modalities to minimize long-term health risks, which makes contrast ultrasound an ideal choice for diagnosing congenital heart defects, liver lesions, and vascular abnormalities in children.
- Similarly, interventional radiology increasingly relies on real-time imaging guidance for procedures such as tumor ablation, biopsy targeting, and vascular interventions. According to the Radiological Society of North America, contrast-enhanced sonography has become essential in guiding minimally invasive treatments, particularly in oncology and hepatology.
- This dual expansion into pediatric care and interventional procedures not only broadens the addressable patient population but also encourages hospitals and ambulatory surgical centers to invest in advanced imaging technologies that support diverse clinical workflows.
Key growth restraining factors of the global contrast ultrasound market:
- Limited reimbursement coverage in several developing markets is constraining adoption rates
- Regulatory complexities related to approval of contrast agents can delay product launches
- Lack of awareness and training among sonographers may limit optimal utilization
- Competition from alternative imaging modalities, such as MRI and CT scans, may restrict market penetration
- Competition from alternative imaging modalities such as MRI and CT scans presents a notable challenge to market growth. While contrast enhanced ultrasound offers radiation-free imaging and real-time capabilities, MRI provides superior soft tissue contrast, and CT delivers comprehensive anatomical detail with faster scan times.
- Many healthcare institutions already have significant investments in MRI and CT infrastructure, which creates institutional inertia against adopting new ultrasound technologies. Additionally, reimbursement policies in several regions favor established imaging modalities over newer contrast ultrasound techniques, particularly for complex diagnostic applications in oncology and cardiology.
- As reported by the American College of Radiology, institutional preferences and physician familiarity with traditional cross-sectional imaging continue to influence diagnostic pathway decisions. This competitive pressure may slow adoption rates in markets where MRI and CT services are well-established and heavily utilized.
KEY MARKET TRENDS
Global Contrast Ultrasound Industry | Top Trends
- Research institutions and pharmaceutical companies are actively developing molecule-targeted microbubbles that bind to specific cellular markers, enabling early detection of tumors, inflammation, and cardiovascular disease. These nanoparticle molecule-targeted agents open new possibilities for precision medicine by allowing clinicians to visualize molecular processes in vivo. According to the National Institutes of Health, ongoing clinical trials are evaluating targeted ultrasound contrast agents for cancer detection and monitoring therapeutic response. This innovation extends the clinical value of contrast enhanced ultrasound beyond anatomical imaging into functional and molecular diagnostics.
- AI-powered image analysis tools are being embedded into modern ultrasound systems to automate image optimization, lesion detection, and quantitative perfusion analysis. These advanced imaging technologies reduce operator dependency and improve diagnostic consistency across different healthcare settings. Leading manufacturers like GE Healthcare and Siemens Healthineers have introduced AI-enhanced platforms that streamline workflow efficiency and support evidence-based decision-making. The integration of machine learning algorithms accelerates image interpretation, which is particularly beneficial in high-volume clinical environments.
- The development of compact, portable ultrasound devices has enabled contrast-enhanced imaging in emergency departments, intensive care units, and rural health centers where traditional imaging infrastructure may be limited. Point-of-care systems facilitate rapid bedside assessments, improving patient outcomes in time-sensitive scenarios such as trauma and acute cardiac events. As noted by the World Health Organization, portable diagnostic tools are critical for expanding healthcare access in underserved regions. This trend supports broader adoption of enhanced ultrasound technology across diverse care settings.
- Partnerships between contrast agent manufacturers and ultrasound equipment providers are yielding integrated solutions optimized for clinical performance and regulatory approval. These collaborations expedite the translation of research innovations into commercially viable products while ensuring compatibility across hardware and software platforms. Recent agreements focus on developing software application diagnostic therapeutic systems that combine real-time imaging with targeted drug delivery mechanisms, creating synergies between diagnostic imaging and personalized treatment approaches.
MARKET SEGMENTATION
Market Segmentation – Product, Type, Application, and End Use –
Market by Product:
- Equipment
- Ultrasound equipment represents the hardware infrastructure essential for conducting contrast enhanced ultrasound procedures. This segment includes advanced ultrasound systems equipped with specialized imaging modes such as contrast-specific imaging, harmonic imaging, and perfusion quantification software. High-end systems feature enhanced signal processing capabilities that optimize microbubble detection while suppressing background tissue signals.
- Moreover, modern equipment integrates AI-driven automation to standardize image quality and reduce variability across different operators. Key features that appeal to healthcare providers include superior image resolution, user-friendly interfaces, touchscreen controls, and compatibility with various contrast agents.
- Demand for this sub-segment is driven by the ongoing replacement of aging ultrasound systems, hospital infrastructure upgrades, and the introduction of portable devices suited for point-of-care applications. Regulatory approvals from agencies like the US. Food and Drug Administration (FDA) have expanded the clinical indications for contrast-enhanced imaging, encouraging hospitals and ambulatory surgical centers to invest in next-generation systems.
- Furthermore, competitive pricing strategies and flexible financing options from manufacturers enable smaller clinics and diagnostic centers to adopt this technology. This sub-segment supports overall market growth by establishing the foundational infrastructure necessary for widespread adoption of contrast ultrasound across diverse healthcare settings.
- Contrast Agents
Market by Type:
- Non-Targeted
- Targeted
Market by Application:
- Diagnostic Applications
- Therapeutic Applications
Market by End Use:
- Hospitals
- Clinics
- Ambulatory Diagnostic Centers
Geographical Study based on Four Major Regions:
- North America: The United States and Canada
- Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, and Rest of Asia-Pacific
- China’s contrast ultrasound market is experiencing robust growth driven by government initiatives to modernize healthcare infrastructure, rising incidence of chronic diseases, and increasing adoption of advanced imaging technologies in tier-2 and tier-3 cities. The Chinese government has prioritized expanding diagnostic capabilities through its Healthy China 2030 initiative, which allocates substantial funding for medical equipment procurement and clinical training programs.
- Additionally, China’s aging population and rising prevalence of liver diseases and cardiovascular conditions are creating significant demand for non-invasive, radiation-free imaging solutions. Domestic manufacturers like Shenzhen Mindray Bio-Medical Electronics are introducing cost-effective ultrasound systems tailored to local market needs, thereby improving accessibility and affordability.
- Furthermore, regulatory reforms by the National Medical Products Administration (NMPA) have streamlined approval processes for new contrast agents and imaging devices, accelerating market entry for innovative products. Challenges remain, however, including limited reimbursement coverage in rural areas and the need for extensive training programs to enhance sonographer proficiency in contrast-enhanced techniques.
- Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the contrast ultrasound market, providing detailed insights into:
MAJOR PLAYERS
The major players in the global contrast ultrasound market are:
- GE Healthcare
- Bracco Imaging SpA
- Lantheus Holdings Inc
- Siemens Healthineers AG
- Koninklijke Philips NV
Key strategies adopted by some of these companies:
- In January 2025, GE Healthcare announced a $138 million investment to expand its contrast media manufacturing facility in Carrigtohill, Cork, Ireland. This business expansion will enable production of an additional 25 million patient doses annually by the end of 2027, addressing the growing global demand for diagnostic imaging agents used in CT scans and X-ray procedures. The strategic investment strengthens supply chain resilience and positions GE Healthcare to meet anticipated market growth as global demand for contrast media is expected to double over the next decade.
- In November 2024, Bracco Imaging inaugurated its Hexagon facility in Plan-les-Ouates, Geneva, with an investment exceeding 80 million euros. This new manufacturing facility, constructed alongside the company’s historical 1996 plant, will triple the production capacity of microbubble-based ultrasound contrast agents when fully operational. The strategic expansion responds to increasing global demand for contrast enhanced ultrasound technology and reinforces Bracco’s leadership position in the CEUS market while supporting both diagnostic imaging and emerging therapeutic applications.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product, Type, Application, End Use |
| Geographies Analyzed | North America, Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | GE HealthCare, Bracco Imaging SpA, Lantheus Holdings Inc, Siemens Healthineers AG, Koninklijke Philips NV, Bayer AG, Guerbet, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, Samsung Healthcare, Daiichi Sankyo Company Limited, Trivitron Healthcare Pvt Ltd, SuperSonic Imagine SA |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE CONTRAST ULTRASOUND MARKET IS EXPANDING STEADILY DUE TO RISING ADOPTION OF MICROBUBBLE-BASED IMAGING AGENTS IN CARDIOLOGY AND ONCOLOGY DIAGNOSTICS
- HOSPITALS REPRESENT THE LARGEST END-USER SEGMENT AS CONTRAST-ENHANCED ULTRASOUND IS INCREASINGLY USED FOR REAL-TIME PERFUSION ASSESSMENT
- EUROPE AND NORTH AMERICA DRIVE MARKET REVENUE DUE TO ESTABLISHED REIMBURSEMENT FRAMEWORKS AND CLINICAL GUIDELINES
- ASIA-PACIFIC IS EMERGING AS A HIGH-GROWTH REGION DRIVEN BY EXPANDING DIAGNOSTIC INFRASTRUCTURE AND RISING AWARENESS OF NON-IONIZING IMAGING MODALITIES
MARKET DYNAMICS
- KEY DRIVERS
- RISING PREVALENCE OF CARDIOVASCULAR DISEASES AND LIVER DISORDERS IS INCREASING DEMAND FOR ENHANCED DIAGNOSTIC ACCURACY
- GROWING PREFERENCE FOR MINIMALLY INVASIVE AND RADIATION-FREE IMAGING TECHNIQUES IS BOOSTING CONTRAST ULTRASOUND UTILIZATION
- TECHNOLOGICAL ADVANCEMENTS IN ULTRASOUND SYSTEMS ARE IMPROVING IMAGE RESOLUTION AND CLINICAL CONFIDENCE
- EXPANDING CLINICAL APPLICATIONS IN PEDIATRICS AND INTERVENTIONAL RADIOLOGY ARE BROADENING MARKET OPPORTUNITIES
- KEY RESTRAINTS
- LIMITED REIMBURSEMENT COVERAGE IN SEVERAL DEVELOPING MARKETS IS CONSTRAINING ADOPTION RATES
- REGULATORY COMPLEXITIES RELATED TO APPROVAL OF CONTRAST AGENTS CAN DELAY PRODUCT LAUNCHES
- LACK OF AWARENESS AND TRAINING AMONG SONOGRAPHERS MAY LIMIT OPTIMAL UTILIZATION
- COMPETITION FROM ALTERNATIVE IMAGING MODALITIES SUCH AS MRI AND CT SCANS MAY RESTRICT MARKET PENETRATION
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING RESEARCH ON TARGETED MICROBUBBLE CONTRAST AGENTS IS DRIVING INNOVATION IN MOLECULAR IMAGING
- GROWING INTEGRATION OF ARTIFICIAL INTELLIGENCE IN ULTRASOUND WORKFLOWS IS ENHANCING DIAGNOSTIC PRECISION
- SHIFT TOWARD POINT-OF-CARE ULTRASOUND DEVICES IS EXPANDING ACCESS TO CONTRAST-ENHANCED STUDIES
- STRATEGIC COLLABORATIONS BETWEEN PHARMACEUTICAL AND MEDICAL DEVICE COMPANIES ARE ACCELERATING PRODUCT DEVELOPMENT
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
- GROWTH PROSPECT MAPPING FOR REST OF WORLD
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- CONTRAST AGENT MANUFACTURERS
- ULTRASOUND OEMS
- DISTRIBUTION PARTNERS
- HOSPITAL PROCUREMENT
- END-USER FACILITIES
- KEY BUYING CRITERIA
- IMAGE CLARITY
- SAFETY PROFILE
- REGULATORY APPROVAL
- COST EFFECTIVENESS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CONTRAST ULTRASOUND MARKET BY PRODUCT
- EQUIPMENT
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CONTRAST AGENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EQUIPMENT
CONTRAST ULTRASOUND MARKET BY TYPE
- NON-TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NON-TARGETED
CONTRAST ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CONTRAST ULTRASOUND MARKET BY END USE
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CLINICS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA MARKET DRIVERS
- NORTH AMERICA MARKET CHALLENGES
- KEY PLAYERS IN NORTH AMERICA CONTRAST ULTRASOUND MARKET
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE CONTRAST ULTRASOUND MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- ASIA-PACIFIC
- MARKET SIZE & ESTIMATES
- ASIA-PACIFIC MARKET DRIVERS
- ASIA-PACIFIC MARKET CHALLENGES
- KEY PLAYERS IN ASIA-PACIFIC CONTRAST ULTRASOUND MARKET
- COUNTRY ANALYSIS
- CHINA
- CHINA MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET SIZE & ESTIMATES
- REST OF WORLD MARKET DRIVERS
- REST OF WORLD MARKET CHALLENGES
- KEY PLAYERS IN REST OF WORLD CONTRAST ULTRASOUND MARKET
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BRACCO IMAGING SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LANTHEUS HOLDINGS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BAYER AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GUERBET
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DAIICHI SANKYO COMPANY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE PVT LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUPERSONIC IMAGINE SA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CONTRAST ULTRASOUND
TABLE 2: CONTRAST ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: EQUIPMENT MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: EQUIPMENT MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: CONTRAST AGENTS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: CONTRAST AGENTS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: NON-TARGETED MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: NON-TARGETED MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: TARGETED MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 14: TARGETED MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 15: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 16: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 17: DIAGNOSTIC APPLICATIONS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 18: DIAGNOSTIC APPLICATIONS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 19: THERAPEUTIC APPLICATIONS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 20: THERAPEUTIC APPLICATIONS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 21: MARKET BY END USE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 22: MARKET BY END USE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 23: HOSPITALS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 24: HOSPITALS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 25: CLINICS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 26: CLINICS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 27: AMBULATORY DIAGNOSTIC CENTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 28: AMBULATORY DIAGNOSTIC CENTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 29: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 30: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 31: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 32: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 33: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 34: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 35: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 36: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 37: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 38: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 39: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 40: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 41: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 42: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 43: LIST OF MERGERS & ACQUISITIONS
TABLE 44: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 45: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 46: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 6: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 7: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 8: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 9: MARKET MATURITY ANALYSIS
FIGURE 10: MARKET CONCENTRATION ANALYSIS
FIGURE 11: VALUE CHAIN ANALYSIS
FIGURE 12: KEY BUYING CRITERIA
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY PRODUCT, IN 2025
FIGURE 14: EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: CONTRAST AGENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 17: NON-TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 20: DIAGNOSTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: THERAPEUTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY END USE, IN 2025
FIGURE 23: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: CLINICS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: AMBULATORY DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: NORTH AMERICA CONTRAST ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 27: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: EUROPE CONTRAST ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 30: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 37: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: ASIA-PACIFIC CONTRAST ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 39: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 42: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 44: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 48: REST OF WORLD CONTRAST ULTRASOUND MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 49: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
Contrast enhanced ultrasound is an advanced diagnostic imaging technique that uses injectable microbubble-based contrast agents to improve the visualization of blood flow and tissue perfusion. Unlike standard ultrasound, which relies solely on reflected sound waves from tissues, contrast ultrasound enhances image clarity by highlighting vascular structures and organ perfusion patterns in real-time, making it particularly valuable for detecting tumors, assessing liver lesions, and evaluating cardiac function.
The market is primarily driven by diagnostic applications in cardiology, oncology, and hepatology, where enhanced imaging supports early disease detection and treatment monitoring. Additionally, therapeutic applications such as targeted drug delivery and tumor ablation guidance are gaining traction. The technology’s radiation-free nature and real-time imaging capabilities make it especially suitable for pediatric patients and interventional radiology procedures.
Asia-Pacific is anticipated to exhibit the highest growth rate due to expanding healthcare infrastructure, rising prevalence of chronic diseases, and increasing government investments in advanced imaging technologies. China and India are particularly promising markets given their large patient populations and ongoing efforts to improve diagnostic capabilities. Meanwhile, North America and Europe continue to dominate in terms of market value, supported by well-established reimbursement frameworks and clinical guidelines that favor the adoption of enhanced ultrasound industry innovations.
RELATED REPORTS
-
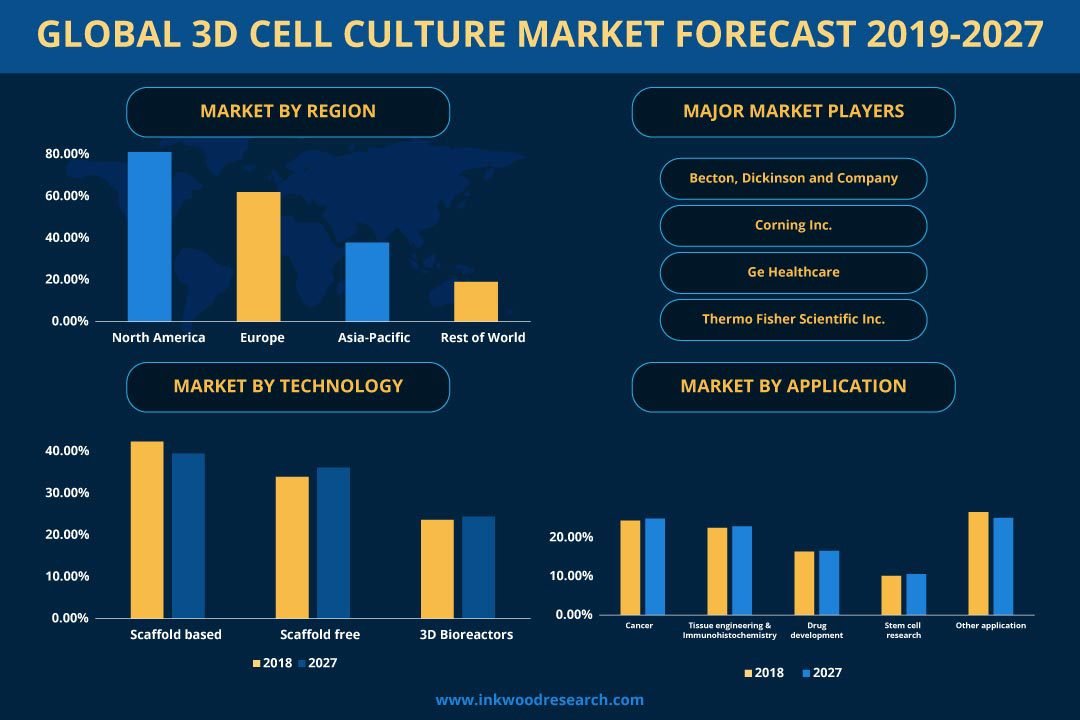
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
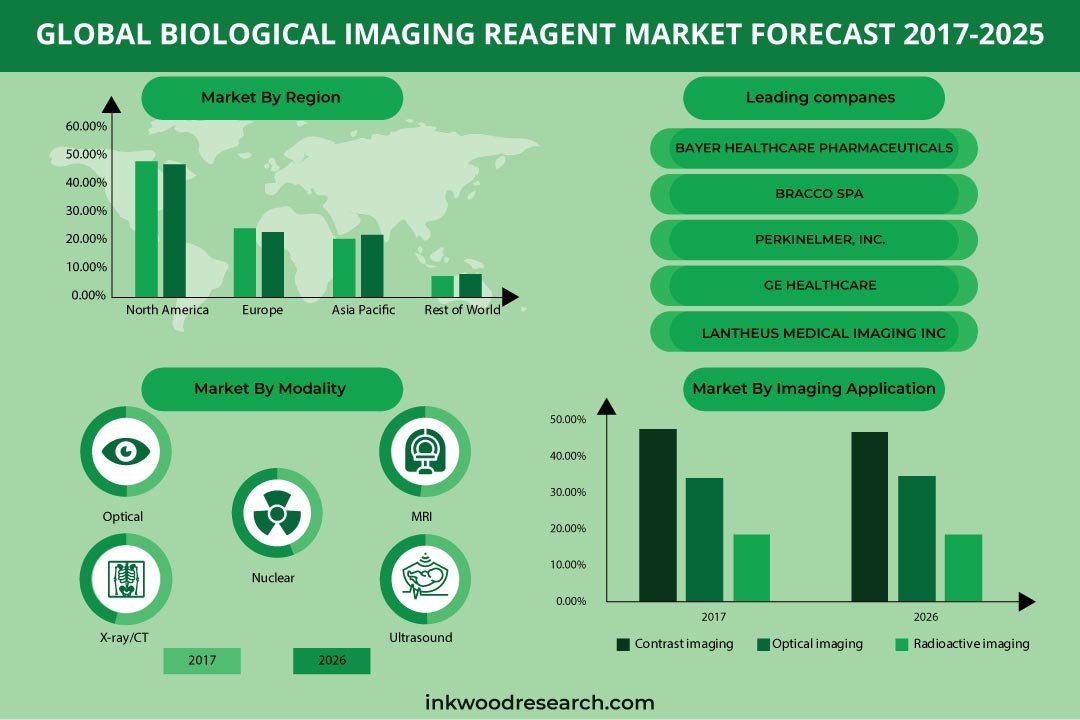
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
SPAIN ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
MEXICO ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
BRAZIL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
INDIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
GLOBAL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034