Global Cardiovascular Ultrasound Market by Device Display (Color Display Systems, Black & White (B/W) Display Systems) Market by Technology (2D Ultrasound, 3D & 4D Ultrasound, Doppler Imaging) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by Type (Transthoracic Echocardiogram, Transesophageal Echocardiogram, Stress Echocardiogram, Fetal Echocardiography, Other Types) Market by End-User (Hospitals, Diagnostic Centers, Ambulatory Care Centers, Other End-Users), by Geography
GLOBAL CARDIOVASCULAR ULTRASOUND MARKET OVERVIEW
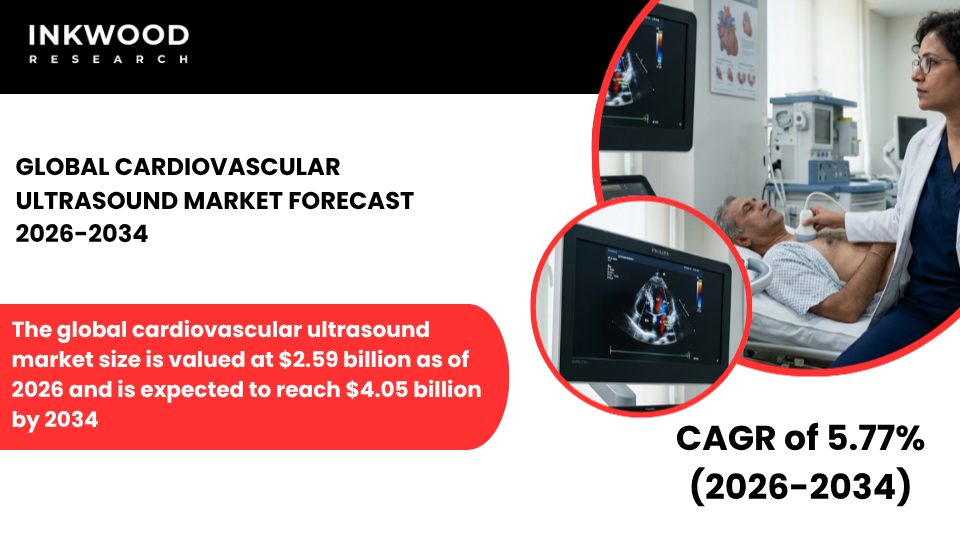
The global cardiovascular ultrasound market size is valued at $2.59 billion as of 2026 and is expected to reach $4.05 billion by 2034, growing at a CAGR of 5.77% during the forecast period 2026–2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the cardiovascular ultrasound market qualitatively as well as quantitatively.
Cardiovascular ultrasound, commonly referred to as cardiac ultrasound or echocardiography, is a non-invasive diagnostic imaging modality that uses high-frequency sound waves, or ultrasound frequencies, to produce real-time images of the heart’s structure, function, and surrounding blood vessels. These systems capture detailed views of cardiac chambers, valves, and myocardial tissue without the use of radiation, making them one of the most widely adopted tools in advanced cardiovascular care today.
The technology spans multiple modalities, including the transthoracic echocardiogram, transesophageal echocardiogram, stress echocardiogram, fetal echocardiography, and Doppler imaging by modality, each serving a distinct clinical purpose. From routine screening and cardiac diagnostic procedures in hospitals and ambulatory care centers to complex interventional guidance, cardiovascular ultrasound offers a versatile and cost-effective alternative to CT and MRI.
As a cornerstone of both biomedical electronics and cardiovascular imaging, these systems are integral to managing the rising global burden of cardiovascular diseases. Advances in 2D, 3D, and 4D imaging, along with AI integration and handheld echocardiography, are further expanding the scope and clinical relevance of this technology across diverse healthcare settings worldwide.
The global cardiovascular ultrasound market is witnessing sustained momentum, driven by the escalating prevalence of cardiovascular diseases, a rapidly aging global population, and growing demand for non-invasive cardiac diagnostic procedures. As per data published by the Global Burden of Disease 2023 study in JACC, global deaths from cardiovascular disease (CVD) increased from 12.4 million in 1990 to 19.8 million in 2022, reflecting both population growth and the mounting burden of preventable metabolic and behavioral risk factors.
This expanding disease burden is directly fueling demand for cardiac ultrasound systems across hospitals, ambulatory care centers, and diagnostic centers globally. Meanwhile, rapid technological innovation, from AI-assisted image interpretation to portable and handheld echocardiography, is reshaping clinical workflows and bringing advanced cardiovascular imaging market capabilities to even remote and resource-limited settings.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global cardiovascular ultrasound market growth:
- The increasing prevalence of hypertension, coronary artery disease, and heart failure is driving demand for routine cardiac imaging
- Technological advancements such as 3D and 4D echocardiography are enhancing diagnostic accuracy and clinical adoption
- Growing geriatric populations worldwide are contributing to a higher incidence of cardiac disorders and follow-up imaging needs
- Rising awareness of preventive healthcare and early disease detection is supporting expanded use of cardiovascular ultrasound
- Rising health awareness and the global shift toward preventive medicine represent one of the most consequential growth levers for the cardiac ultrasound systems market. As healthcare systems worldwide prioritize early disease detection to reduce the long-term cost of chronic cardiovascular disease management, the demand for accessible, non-invasive cardiac diagnostic procedures has surged.
- According to the American Heart Association’s 2025 Heart Disease and Stroke Statistics Update, CVD remains the leading cause of death globally, with the highest mortality rates recorded in Central Asia and Eastern Europe.
- This recognition is prompting governments and healthcare providers to invest in screening programs, population-level cardiac assessments, and expanded access to cardiovascular ultrasound at the community level, particularly in regions with historically limited access to advanced cardiovascular imaging. As patients and clinicians alike embrace proactive cardiac monitoring, the cardiovascular imaging market stands to benefit substantially over the forecast horizon.
Key growth restraining factors of the global cardiovascular ultrasound market:
- High capital costs of advanced ultrasound systems limit adoption in small clinics and resource-constrained settings
- Shortage of skilled sonographers and cardiologists impacts optimal utilization of sophisticated imaging equipment
- Reimbursement limitations in certain regions reduce incentives for frequent cardiac imaging procedures
- Competition from alternative imaging modalities such as CT and MRI may restrain market expansion in complex cases
- Competition from established imaging modalities, particularly CT and MRI, presents a meaningful structural challenge to the cardiovascular ultrasound market, especially for complex cardiac cases. While cardiovascular ultrasound offers clear advantages in terms of cardiac ultrasound cost, real-time imaging capability, and absence of ionizing radiation, CT angiography and cardiac MRI are often preferred for highly complex diagnoses such as structural heart disease, detailed coronary artery assessment, and cardiac tissue characterization.
- In advanced healthcare systems where these modalities are widely reimbursed and readily available, clinicians may choose CT or MRI over echocardiography for certain diagnostic pathways. This competitive dynamic can constrain volume growth for premium cardiac ultrasound machine price segments, particularly in North American and European tertiary care centers, where multi-modality imaging protocols are the standard of care.
KEY MARKET TRENDS
Global Cardiovascular Ultrasound Industry | Top Trends
- AI integration for automated cardiac image interpretation is rapidly transforming the cardiovascular imaging market by reducing diagnostic variability and improving workflow efficiency across hospitals and ambulatory care centers. Companies such as GE HealthCare have already introduced AI-powered tools, including Caption AI on their Vscan Air SL handheld system, which uses deep learning to guide probe positioning and automatically calculate left ventricular ejection fraction (LVEF), a critical measure of cardiac function. As per GE HealthCare’s official RSNA 2024 announcement, these capabilities are specifically designed to reduce diagnostic time and enhance measurement consistency, making advanced cardiovascular ultrasound more accessible even in settings with less experienced operators. As AI becomes embedded across the cardiac ultrasound systems market, the technology is expected to compensate for the global shortage of trained sonographers and cardiologists, thereby broadening the user base.
- The growing adoption of point-of-care and handheld echocardiography is redefining how cardiac diagnostic procedures are performed in emergency departments, intensive care units, and community health settings. This shift toward portable cardiovascular ultrasound is being driven by the mobility and cost-effectiveness of compact devices, which allow bedside cardiac assessments without the need to transport critically ill patients to imaging suites. As the cardiovascular ultrasound machine price for handheld systems continues to decline, with disruptors like Butterfly Network and Clarius offering sub-USD 3,000 devices, adoption is expanding beyond tertiary hospitals to primary care, rural clinics, and telehealth settings.
- Strategic collaborations and acquisitions are accelerating innovation across the cardiac ultrasound systems market, with leading players investing heavily to strengthen their AI and digital diagnostics portfolios. In May 2024, Samsung Medison completed its acquisition of Sonio, a French AI ultrasound analysis firm, to deepen its AI-driven diagnostics capability. Furthermore, Samsung Medison entered a strategic partnership with California-based Exo Imaging in 2025, with a reported equity investment of up to USD 100 million, to co-develop next-generation silicon-based ultrasound platforms for both point-of-care and hospital settings, as reported by Korea BioMed. Similarly, GE HealthCare’s USD 51 million acquisition of Intelligent Ultrasound in 2024 bolstered its real-time AI analytics capabilities. These strategic moves signal an industry-wide pivot toward software-driven, AI-integrated cardiovascular ultrasound platforms that go beyond hardware innovation.
- Rising demand for compact and wireless cardiovascular ultrasound devices is enabling community-level and home-based cardiac monitoring, particularly in rapidly developing economies where healthcare infrastructure is still maturing. This trend is especially pronounced in the Asia-Pacific region, where governments are investing in mobile diagnostic units and tele-echocardiography to extend advanced cardiovascular imaging capabilities to underserved populations. According to the National Center for Biotechnology Information (NCBI), approximately 330 million people in China are affected by cardiovascular conditions, a figure that underscores the acute need for scalable, cost-effective cardiac imaging solutions. The Healthy China 2030 plan has further catalyzed government investment in healthcare infrastructure and digital diagnostics, creating a favorable environment for the deployment of portable cardiovascular ultrasound systems across the country’s vast primary care network.
MARKET SEGMENTATION
Market Segmentation – Device Display, Technology, Application, Type, and End-User –
Market by Device Display:
- Color Display Systems
- Color display systems represent the dominant segment within the cardiovascular ultrasound market by device display, and for good reason. These systems incorporate advanced color Doppler imaging capabilities that allow clinicians to visualize blood flow direction, velocity, and turbulence within the heart in real time, information that is indispensable for assessing valvular pathologies, intracardiac shunts, and hemodynamic abnormalities.
- Color display units enable the simultaneous rendering of anatomical structures and flow data on a single screen, reducing the need for supplementary imaging and streamlining the overall workflow in cardiac diagnostic procedures. The segment’s appeal spans the full spectrum of clinical settings, from high-throughput hospital echo labs to diagnostic centers and ambulatory care centers, where image clarity and diagnostic completeness are non-negotiable.
- Demand for premium color units continues to rise as OLED and high-dynamic-range display panels deliver finer imaging detail and greater diagnostic confidence. Furthermore, the growing integration of AI-driven tissue classification with color overlay features is opening new clinical applications, reinforcing the segment’s dominant position within the global cardiac ultrasound systems market through the forecast period.
- Black & White (B/W) Display Systems
Market by Technology:
- 2D Ultrasound
- 3D & 4D Ultrasound
- Doppler Imaging
Market by Application:
- Diagnostic Applications
- Therapeutic Applications
Market by Type:
- Transthoracic Echocardiogram
- Transesophageal Echocardiogram
- Stress Echocardiogram
- Fetal Echocardiography
- Other Types
Market by End-User:
- Hospitals
- Diagnostic Centers
- Ambulatory Care Centers
- Other End-Users
Geographical Study based on Four Major Regions:
- North America: The United States and Canada
- Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, and Rest of Asia-Pacific
- China represents one of the most strategically significant and high-potential markets within the global cardiovascular imaging market, underpinned by a combination of staggering disease burden, rapid healthcare infrastructure expansion, and supportive government policy. According to the National Center for Biotechnology Information (NCBI), approximately 330 million people in China are affected by cardiovascular conditions, creating an enormous and structurally sustained demand for cardiac diagnostic procedures.
- The Chinese government’s Healthy China 2030 initiative has committed large-scale investments toward upgrading hospital infrastructure, expanding access to diagnostic imaging, and promoting early disease detection, all of which directly benefit the cardiovascular ultrasound market. Domestically, companies such as Mindray continue to expand their market footprint through cost-competitive cardiac ultrasound systems tailored to both premium urban hospitals and cost-sensitive rural facilities.
- On the other hand, foreign players like GE HealthCare established a long-term joint venture with a Chinese state-owned entity in 2023 to deliver non-premium general imaging ultrasound solutions tailored to the domestic market. The convergence of rising cardiovascular disease burden, government-driven healthcare modernization, and growing local manufacturing capability positions China as a critical growth engine for the cardiac ultrasound systems market through 2034.
- Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the cardiovascular ultrasound market, providing detailed insights into –
MAJOR PLAYERS
The major players in the global cardiovascular ultrasound market are:
- GE Healthcare
- Koninklijke Philips NV
- Siemens Healthineers AG
- Mindray Medical International Limited
- Samsung Medison Co. Ltd.
Key strategies adopted by some of these companies:
- GE HealthCare acquired Intelligent Ultrasound for USD 51 million in 2024, significantly strengthening its real-time AI analytics capabilities for cardiac ultrasound systems and deepening its competitive positioning in the cardiovascular imaging market. This acquisition directly integrated advanced AI image interpretation tools into GE’s existing portfolio, including its widely adopted Vscan Air handheld echocardiography line.
- Samsung Medison entered a strategic partnership with California-based Exo Imaging in May 2025, backed by a reported equity investment of up to USD 100 million from Samsung Venture Investment Corporation. The collaboration aims to co-develop next-generation, silicon-based ultrasound platforms combining Exo’s high-performance handheld technology with Samsung Medison’s global engineering and commercial reach, targeting both point-of-care and hospital-based cardiovascular ultrasound applications.
- Siemens Healthineers unveiled its Optiq AI imaging platform at RSNA 2025 in November 2025, introducing AI-driven imaging capabilities across three new cardiovascular and interventional systems: the Artis genio, Artis icono.explore, and Artis icono.vision/Artis pheno.vision. Optiq AI automates exposure parameters and applies live noise-reduction algorithms during fluoroscopy and angiography, directly enhancing precision for minimally invasive cardiovascular procedures and reinforcing Siemens Healthineers’ advanced cardiovascular diagnostics leadership.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Device Display, Technology, Type, End-User |
| Geographies Analyzed | North America, Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | Analogic Corporation, Canon Medical Systems Corporation, CHISON Medical Technologies Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation (FUJIFILM SonoSite Inc), GE Healthcare, Hitachi Medical Corporation, Konica Minolta Inc, Koninklijke Philips NV, Mindray Medical International Limited, Samsung Medison Co Ltd, Siemens Healthineers AG, Trivitron Healthcare, Whale Imaging Inc, Zonare Medical Systems (part of Mindray) |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE CARDIOVASCULAR ULTRASOUND MARKET IS EXPANDING STEADILY DUE TO THE RISING BURDEN OF CARDIOVASCULAR DISEASES AND THE INCREASING NEED FOR EARLY AND NON-INVASIVE DIAGNOSTICS
- HOSPITALS ACCOUNT FOR THE LARGEST SHARE OF REVENUE, DRIVEN BY HIGH PROCEDURE VOLUMES AND CONTINUOUS UPGRADES TO ADVANCED ECHOCARDIOGRAPHY SYSTEMS
- PORTABLE AND HANDHELD CARDIAC ULTRASOUND DEVICES ARE GAINING TRACTION ACROSS EMERGENCY AND POINT OF CARE SETTINGS DUE TO THEIR MOBILITY AND COST EFFECTIVENESS
- DEVELOPED MARKETS DOMINATE REVENUE SHARE, WHILE EMERGING ECONOMIES ARE WITNESSING FASTER GROWTH DUE TO EXPANDING HEALTHCARE INFRASTRUCTURE AND SCREENING PROGRAMS
MARKET DYNAMICS
- KEY DRIVERS
- THE INCREASING PREVALENCE OF HYPERTENSION, CORONARY ARTERY DISEASE, AND HEART FAILURE IS DRIVING DEMAND FOR ROUTINE CARDIAC IMAGING
- TECHNOLOGICAL ADVANCEMENTS SUCH AS 3D AND 4D ECHOCARDIOGRAPHY ARE ENHANCING DIAGNOSTIC ACCURACY AND CLINICAL ADOPTION
- GROWING GERIATRIC POPULATIONS WORLDWIDE ARE CONTRIBUTING TO HIGHER INCIDENCE OF CARDIAC DISORDERS AND FOLLOW-UP IMAGING NEEDS
- RISING AWARENESS OF PREVENTIVE HEALTHCARE AND EARLY DISEASE DETECTION IS SUPPORTING EXPANDED USE OF CARDIOVASCULAR ULTRASOUND
- KEY RESTRAINTS
- HIGH CAPITAL COSTS OF ADVANCED ULTRASOUND SYSTEMS LIMIT ADOPTION IN SMALL CLINICS AND RESOURCE-CONSTRAINED SETTINGS
- SHORTAGE OF SKILLED SONOGRAPHERS AND CARDIOLOGISTS IMPACTS OPTIMAL UTILIZATION OF SOPHISTICATED IMAGING EQUIPMENT
- REIMBURSEMENT LIMITATIONS IN CERTAIN REGIONS REDUCE INCENTIVES FOR FREQUENT CARDIAC IMAGING PROCEDURES
- COMPETITION FROM ALTERNATIVE IMAGING MODALITIES SUCH AS CT AND MRI MAY RESTRAIN MARKET EXPANSION IN COMPLEX CASES
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INTEGRATION OF ARTIFICIAL INTELLIGENCE FOR AUTOMATED IMAGE INTERPRETATION IS IMPROVING WORKFLOW EFFICIENCY AND REDUCING DIAGNOSTIC VARIABILITY
- GROWING ADOPTION OF POINT OF CARE ULTRASOUND IN EMERGENCY AND INTENSIVE CARE UNITS IS TRANSFORMING CARDIAC ASSESSMENT PRACTICES
- INCREASING DEMAND FOR COMPACT AND WIRELESS DEVICES IS ENABLING COMMUNITY LEVEL AND HOME-BASED CARDIAC MONITORING
- STRATEGIC COLLABORATIONS BETWEEN DEVICE MANUFACTURERS AND HEALTHCARE PROVIDERS ARE ACCELERATING TECHNOLOGY DEPLOYMENT AND TRAINING INITIATIVES
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
- GROWTH PROSPECT MAPPING FOR REST OF WORLD
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- COMPONENT MANUFACTURERS
- SYSTEM INTEGRATORS
- DEVICE MANUFACTURERS
- DISTRIBUTION CHANNELS
- HEALTHCARE PROVIDERS
- AFTER SALES SERVICES
- KEY BUYING CRITERIA
- IMAGE RESOLUTION
- PORTABILITY FEATURES
- TOTAL COST OWNERSHIP
- SERVICE SUPPORT AVAILABILITY
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CARDIOVASCULAR ULTRASOUND MARKET BY DEVICE DISPLAY
- COLOR DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- BLACK & WHITE (B/W) DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COLOR DISPLAY SYSTEMS
CARDIOVASCULAR ULTRASOUND MARKET BY TECHNOLOGY
- 2D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 3D & 4D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DOPPLER IMAGING
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 2D ULTRASOUND
CARDIOVASCULAR ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CARDIOVASCULAR ULTRASOUND MARKET BY TYPE
- TRANSTHORACIC ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSESOPHAGEAL ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- STRESS ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- FETAL ECHOCARDIOGRAPHY
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER TYPES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSTHORACIC ECHOCARDIOGRAM
CARDIOVASCULAR ULTRASOUND MARKET BY END-USER
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY CARE CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER END-USERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA MARKET DRIVERS
- NORTH AMERICA MARKET CHALLENGES
- KEY PLAYERS IN NORTH AMERICA CARDIOVASCULAR ULTRASOUND MARKET
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE CARDIOVASCULAR ULTRASOUND MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- ASIA-PACIFIC
- MARKET SIZE & ESTIMATES
- ASIA-PACIFIC MARKET DRIVERS
- ASIA-PACIFIC MARKET CHALLENGES
- KEY PLAYERS IN ASIA-PACIFIC CARDIOVASCULAR ULTRASOUND MARKET
- COUNTRY ANALYSIS
- CHINA
- CHINA MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET SIZE & ESTIMATES
- REST OF WORLD MARKET DRIVERS
- REST OF WORLD MARKET CHALLENGES
- KEY PLAYERS IN REST OF WORLD CARDIOVASCULAR ULTRASOUND MARKET
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- ANALOGIC CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CHISON MEDICAL TECHNOLOGIES CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION (FUJIFILM SONOSITE, INC.)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- HITACHI MEDICAL CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONICA MINOLTA INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- MINDRAY MEDICAL INTERNATIONAL LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG MEDISON CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- WHALE IMAGING INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ZONARE MEDICAL SYSTEMS (PART OF MINDRAY)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ANALOGIC CORPORATION
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CARDIOVASCULAR ULTRASOUND
TABLE 2: CARDIOVASCULAR ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY DEVICE DISPLAY, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY DEVICE DISPLAY, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: COLOR DISPLAY SYSTEMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: COLOR DISPLAY SYSTEMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: BLACK & WHITE (B/W) DISPLAY SYSTEMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: BLACK & WHITE (B/W) DISPLAY SYSTEMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY TECHNOLOGY, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY TECHNOLOGY, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: 2D ULTRASOUND MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: 2D ULTRASOUND MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: 3D & 4D ULTRASOUND MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 14: 3D & 4D ULTRASOUND MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 15: DOPPLER IMAGING MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 16: DOPPLER IMAGING MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 17: MARKET BY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 18: MARKET BY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 19: TRANSTHORACIC ECHOCARDIOGRAM MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 20: TRANSTHORACIC ECHOCARDIOGRAM MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 21: TRANSESOPHAGEAL ECHOCARDIOGRAM MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 22: TRANSESOPHAGEAL ECHOCARDIOGRAM MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 23: STRESS ECHOCARDIOGRAM MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 24: STRESS ECHOCARDIOGRAM MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 25: FETAL ECHOCARDIOGRAPHY MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 26: FETAL ECHOCARDIOGRAPHY MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 27: OTHER TYPES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 28: OTHER TYPES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 29: MARKET BY END-USER, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 30: MARKET BY END-USER, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 31: HOSPITALS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 32: HOSPITALS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 33: DIAGNOSTIC CENTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 34: DIAGNOSTIC CENTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 35: AMBULATORY CARE CENTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 36: AMBULATORY CARE CENTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 37: OTHER END-USERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 38: OTHER END-USERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 39: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 40: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 41: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 42: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 43: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 44: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 45: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 46: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 47: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 48: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 49: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 50: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 51: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 52: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 53: LIST OF MERGERS & ACQUISITIONS
TABLE 54: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 55: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 56: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 6: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 7: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 8: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 9: MARKET MATURITY ANALYSIS
FIGURE 10: MARKET CONCENTRATION ANALYSIS
FIGURE 11: VALUE CHAIN ANALYSIS
FIGURE 12: KEY BUYING CRITERIA
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY DEVICE DISPLAY, IN 2025
FIGURE 14: COLOR DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: BLACK & WHITE (B/W) DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY TECHNOLOGY, IN 2025
FIGURE 17: 2D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: 3D & 4D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: DOPPLER IMAGING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 21: TRANSTHORACIC ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: TRANSESOPHAGEAL ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: STRESS ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: FETAL ECHOCARDIOGRAPHY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: OTHER TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 27: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: AMBULATORY CARE CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: NORTH AMERICA CARDIOVASCULAR ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 32: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: EUROPE CARDIOVASCULAR ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 35: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 37: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 39: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 42: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: ASIA-PACIFIC CARDIOVASCULAR ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 44: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 48: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 49: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 51: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 52: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 53: REST OF WORLD CARDIOVASCULAR ULTRASOUND MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 54: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 55: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
The global cardiovascular ultrasound market includes echocardiography systems and cardiac imaging devices used for non-invasive heart disease diagnosis, driven by rising cardiovascular disease prevalence, AI-enabled imaging innovations, portable ultrasound adoption, and demand for early, cost effective cardiac screening.
Transthoracic echocardiography holds the largest share of the cardiovascular ultrasound market due to its non-invasive nature, broad clinical applications, and routine use in hospitals and outpatient cardiac diagnostic centers worldwide.
Cardiovascular ultrasound machine prices range from under USD 3000 for handheld echocardiography devices to over USD 300000 for advanced cart-based 3D and AI-enabled cardiac ultrasound systems, depending on features and portability.
Major end users include hospitals, cardiac specialty clinics, diagnostic imaging centers, and ambulatory care facilities seeking advanced echocardiography systems for heart disease diagnosis and ongoing patient monitoring.
AI-powered cardiovascular ultrasound systems enhance image quality, automate measurements, reduce operator dependency, improve workflow efficiency, and enable faster and more accurate cardiac disease detection in clinical practice.
Growing demand for point-of-care cardiac imaging, rural healthcare expansion, emergency department diagnostics, and cost-sensitive healthcare settings are accelerating the adoption of portable and handheld echocardiography devices globally.
RELATED REPORTS
-
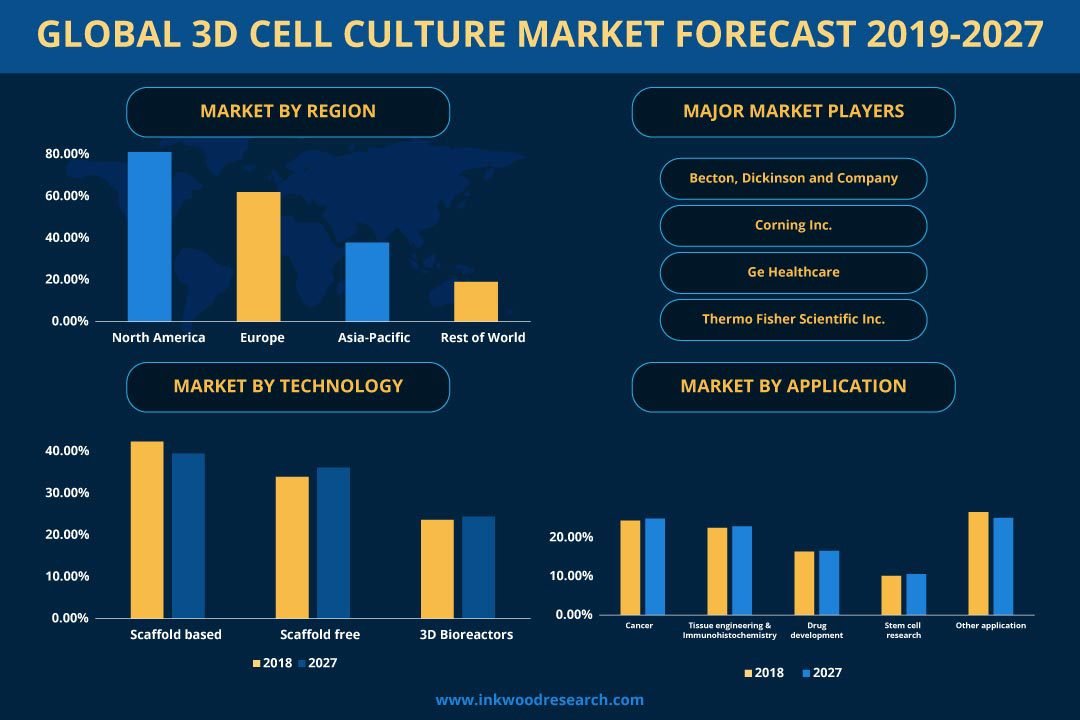
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
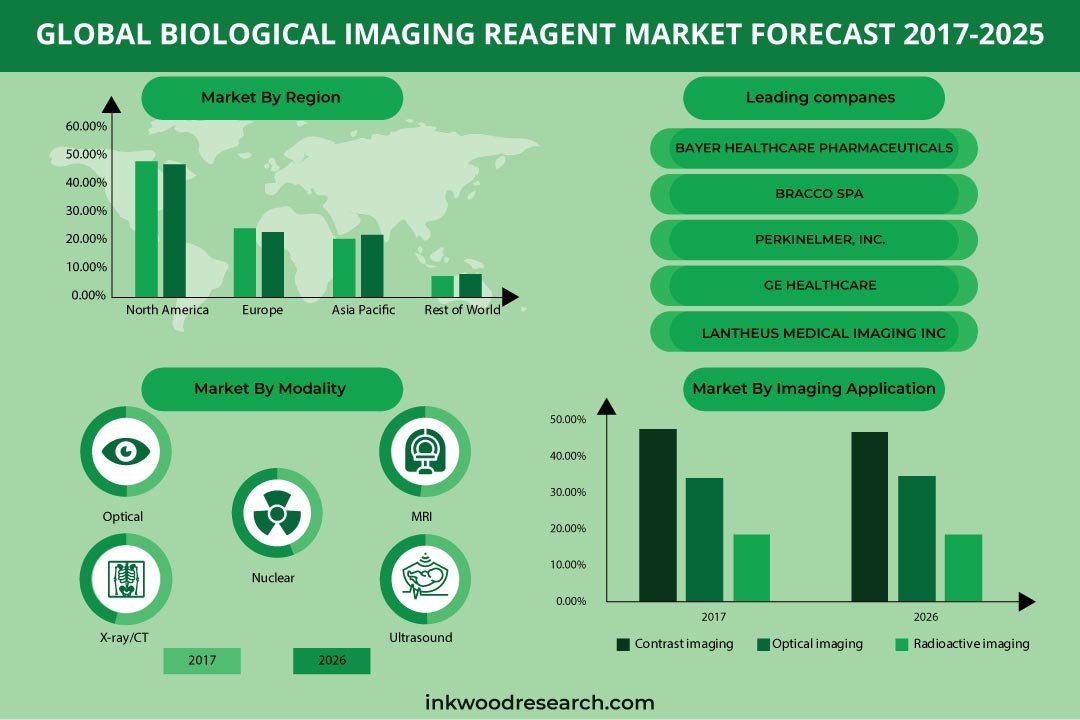
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
SPAIN ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
MEXICO ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
BRAZIL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
INDIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
GLOBAL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034